economy

The luxury industry is confronting one of its most uncomfortable questions in years: how far…

The Kingdom is moving from exporting luxury spending to capturing it at home For decades,…


Abu Dhabi wants to compete with Geneva, London, New York and Hong Kong For decades,…

When a car becomes a luxury object Louis Vuitton has found a new canvas on…

Miss Dior enters the age of personalisation Dior is bringing one of the most effective…

Ralph Lauren has delivered one of the clearest signals yet that the global luxury and…

While much of the international luxury industry continues to wait for a stronger recovery in…

Chinese luxury consumers are spending less on handbags but continuing to invest in prestige beauty, premium skincare and exclusive fragrances.

For much of the past two years, conversations about the luxury industry have centred on…

For more than twenty years, the global luxury industry has spoken about India as the…

The geographical landscape of the global luxury industry is undergoing a profound rebalancing. The United…

Hermès represents the most admired business model in contemporary luxury. While many brands have pursued…

Richemont is one of the major winners in today’s luxury landscape because it is strongly…

The global luxury industry is entering a new era. The extraordinary growth cycle that followed…

Few stories in luxury are being watched as closely as Gucci’s ongoing transformation. The Italian…

The strategic report revealing how different generations consume luxury hospitality across Europe and Spain LUXONOMY…

The historic Italian house Ermenegildo Zegna has initiated a strategic move that goes far beyond…

What only weeks ago appeared to be a fragile recovery for the global luxury industry…

The first quarter of 2026 has marked a turning point for Hermès. The French maison,…

Certified resale is rapidly emerging as one of the most strategic shifts within the global luxury industry. What was once considered a parallel and largely uncontrolled secondary market has evolved into an integrated channel that is reshaping how brands manage value, customer relationships, and product lifecycle.
Leading groups such as LVMH, Kering, and Richemont are increasingly engaging with resale platforms—either by developing their own ecosystems or partnering with established players. The objective is clear: to regain control over a fast-growing market while unlocking new revenue streams and reinforcing brand equity.

In a context of structural transformation in global consumption, leading luxury houses are consolidating a strategic shift toward Ultra High Net Worth (UHNW) clients—individuals with assets exceeding $30 million—as a core driver of growth and long-term stability. This evolution is not temporary; it reflects a precise understanding of changes in wealth distribution, consumer behavior, and the dynamics of the sector itself.
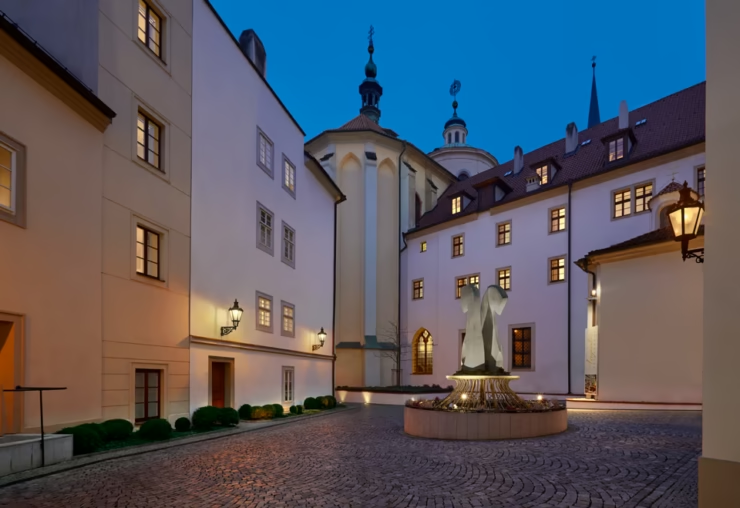
Kempinski Hotels, Europe’s oldest luxury hospitality group, today announces the acquisition of Augustine Hotel, Prague, one of the city’s most historic and prestigious addresses. This wholly owned acquisition marks a significant step in the company’s strategic shift towards an asset-heavier approach to its global portfolio, under the stewardship of Barbara Muckermann, CEO, Kempinski Group. Furthermore, this is the first acquisition for the Group in over 50 years, since the investment in Hotel Vier Jahreszeiten Kempinski Munich in 1970.
The start of 2026 has been tough for major luxury stocks, and the market has once again underscored this forcefully this week. According to data compiled by MarketScreener, since the beginning of the year, LVMH has fallen approximately 26%, Hermès nearly 22%, Richemont 17%, and Kering around 12%. This correction is no mere stock market anecdote; it is a sign that investors no longer view luxury as an automatic safe haven.

The scale of this transition is already measurable. Today, more than 75% of global luxury sales are generated through directly operated channels, compared to roughly 55% a decade ago. For some of the largest luxury groups, direct retail—including both physical boutiques and e-commerce—accounts for over 80% of total revenue. This reflects a clear move toward vertical integration, where distribution is no longer outsourced but becomes a core strategic asset.

There are currently more than 400,000 ultra-wealthy individuals worldwide, with a combined wealth exceeding 45 trillion dollars. When including high-net-worth individuals (HNWIs) with assets above 5 million dollars, the number rises to over 2.5 million globally. Despite representing less than 1% of the population, these consumers account for nearly 30% of total luxury spending, highlighting an unprecedented concentration of purchasing power.

The scale of the opportunity is already tangible. India’s luxury market is estimated at around $12 billion in 2025, with annual growth close to 10%. However, the long-term outlook is where the real strategic value lies. Forecasts suggest that the market could exceed $80 billion by 2030 under high-growth scenarios, fundamentally reshaping the global luxury landscape. Even conservative projections indicate steady expansion, supported by structural economic trends rather than cyclical demand.

Luxury companies have returned to the center of European financial markets in 2026. In a…

The global luxury industry is entering a new phase of strategic consolidation, and one of…

When the economy tightens, the market splits. In the middle, brands fight for a customer…

2026 is not a year of explosive quantitative expansion. It is a year of strategic consolidation, where luxury demonstrates that its greatest strength lies not in speed, but in its ability to adapt intelligently to every new phase of the global market.

The year 2026 is shaping up as a strategic choice phase for listed luxury companies. After an extraordinary expansion cycle between 2021 and 2023, followed by normalization in 2024–2025, the sector is entering a more disciplined environment. In this context, financial institutions like JPMorgan and HSBC have identified specific opportunities grounded in two core pillars: structural brand strength and financial resilience amid mixed global economic conditions.

The geographic center of gravity in luxury is steadily shifting. While Europe remains the historic birthplace of many leading maisons, demand power is increasingly concentrated in Asia and the Middle East. By 2030, China, Japan, the Middle East, and India united represent a dominant share of incremental global luxury growth.
The next chapter of global luxury will not be defined solely by what is produced, but by where wealth is generated and how it flows. In 2026, the map of luxury expansion is unmistakably oriented toward Asia and the Middle East, with India emerging as the next structural force poised to reshape the industry’s long-term trajectory.

The global personal luxury goods market now stands at approximately USD 480 billion, after an accelerated expansion cycle between 2021 and 2024. Although growth has moderated compared to the immediate post-pandemic years, projections for the 2026–2030 period point to an average annual growth rate of 3% to 5%, with Asia, the United States, and the Middle East acting as primary engines. Within this ecosystem, the “hard luxury” segment—jewelry, watchmaking, and durable high-end goods—continues to show stronger resilience than categories more closely tied to seasonal consumption.

If the earlier decade was defined by consolidation and store rollouts, the current one will be shaped by deep cultural integration in emerging regions, experiential tourism aligned with identity and tradition, and Generation Z as architect of commercial design. Saudi Arabia is constructing a platform that blends heritage, innovation, and ambition, while India demonstrates that luxury growth depends on community, narrative, and generational alignment. The global luxury map is no longer drawn exclusively from Paris or Milan. It is increasingly shaped from Riyadh and Mumbai, with a long-term vision that extends well beyond retail and into influence, culture, and systemic transformation.

The American fashion house Ralph Lauren has once again proven that creative consistency, commercial discipline,…